Skip to content
Setcoin Group
CLEAN ENERGY INFRASTRUCTURE • FEED/FID STAGE PROJECTS

DSE Hydrogen & Green Ammonia Fund

Deploying capital into mission-critical hydrogen and green ammonia infrastructure at the FEED and FID stage — targeting electrolysis scale-up, green ammonia production, maritime fuel systems, sustainable aviation fuels, and integrated renewable-to-molecule projects across the $17B+ green hydrogen market growing at 30%+ CAGR through 2033.

Fund type: EquityStatus: Actively Investing

Setcoin Atlas · live pipeline

The pipeline behind the fund

What the public record shows today in the sectors DSE Hydrogen & Green Ammonia Fund invests in. The fund screens from the same Atlas records, and every project is scored on the Bankability Index.

200projects in play: pre-FID with at least one consent gate on the public record7 verified at shovel-ready or later after an in-depth screen
262projects in development (pre-FID)
$17.3bnpre-FID capex (filed or modeled)
191already under construction

By stage (Bankability Index)

  • No gate yet62
  • Award / offtake only66
  • Pre-consent127
  • Shovel-ready0
  • Bankable7

Highlighted rows are in play. Few projects reach shovel-ready or bankable on public evidence alone, because EPC and offtake contracts are rarely published; a Screen on the dataroom moves them. Bars on a square-root scale.

By region

  • Europe & UK229
  • Canada20
  • United States7
  • Middle East & Africa4
  • Latin America2

Verified shortlist: screened in depth, names withheld

#RegionWorking stageReadinessCapexGates on the record
1SpainShovel-ready46$380mlandconsentpermitsgridofftakeepcsponsorcapital
2United Kingdom · ScotlandShovel-ready42$1.2bnlandconsentpermitsgridofftakeepcsponsorcapital
3FinlandShovel-ready30$1.2bnlandconsentpermitsgridofftakeepcsponsorcapital
4DenmarkShovel-ready30$750mlandconsentpermitsgridofftakeepcsponsorcapital
5GermanyShovel-ready30$300mlandconsentpermitsgridofftakeepcsponsorcapital
6DenmarkShovel-ready30$250mlandconsentpermitsgridofftakeepcsponsorcapital
7JordanShovel-ready23$1.0bnlandconsentpermitsgridofftakeepcsponsorcapital
8OmanPre-consent29$4.2bnlandconsentpermitsgridofftakeepcsponsorcapital
9OmanPre-consent26$6.0bnlandconsentpermitsgridofftakeepcsponsorcapital
10MoroccoPre-consent8$4.5bnlandconsentpermitsgridofftakeepcsponsorcapital

Source: Setcoin Atlas — interconnection queues, permit and state registers, award databases. Figures update with each Atlas build. Named projects, sponsors and evidence are available to registered investors in the LP workspace.

Dual-Track Model

The Fund is Currently Raising & Actively Investing

Whether you're an institutional investor seeking exposure to the hydrogen economy, or a hydrogen/ammonia project at FEED or FID stage seeking growth capital, we want to hear from you.

For Ventures & Projects

Submit Your Project

We actively seek hydrogen and green ammonia projects at FEED or FID stage with demonstrated technical viability, secured offtake agreements, and alignment with national hydrogen strategies across priority geographies.

  • Capital at critical development stages
  • Growth equity, project finance, and infrastructure capital
  • Value-add: offtake facilitation, EPC partnerships & permits
  • Access to industrial decarbonization networks
  • Technical due diligence with electrochemical engineering teams
  • Government relations & subsidy capture support
For Investors

Invest in the Fund

Join institutional investors positioning for the energy transition's most capital-intensive build-out phase — green hydrogen and ammonia infrastructure with clear demand visibility from industrial decarbonization and maritime fuel mandates.

  • Exposure to $170-220B infrastructure investment cycle (2026-2030)
  • FEED/FID stage projects with de-risked technical & commercial profiles
  • Long-term contracted offtake revenue backed by industrial demand
  • Government CfD mechanisms and subsidy-backed returns
  • Co-investment opportunities on select mega-projects

Investment Strategy

Building the Molecule Infrastructure for Net-Zero

The DSE Hydrogen & Green Ammonia Fund targets the critical infrastructure bottleneck phase of the energy transition — where abundant renewable generation capacity meets insufficient conversion, storage, and distribution systems. By focusing on FEED and FID stage projects, the fund invests at the inflection point where technical risk has been retired but the capital-intensive build-out phase requires institutional deployment. The 2026–2030 window represents a "build or bust" moment for the hydrogen economy: infrastructure not permitted and started now will not be operational until 2030+, creating a mid-decade bottleneck that could delay climate targets by 5–10 years.

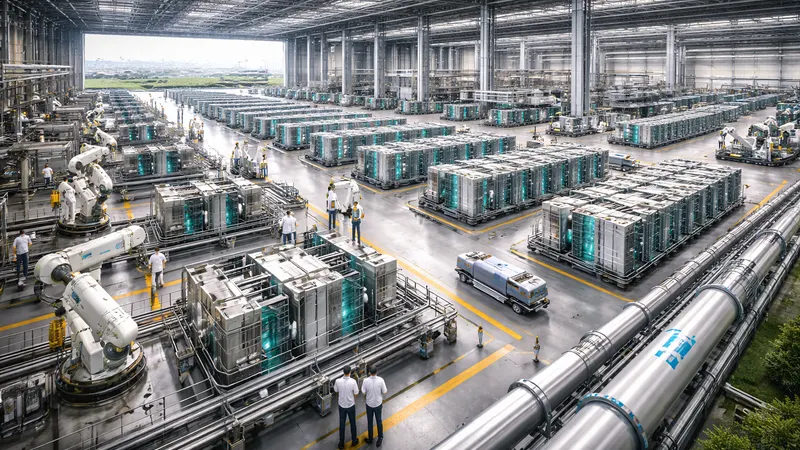
  • Electrolyzer stacks inside a hydrogen production hall

    Electrolysis Technologies

    Alkaline, PEM, SOEC, and AEM electrolyzers — gigafactory construction, catalyst innovation, and 250-300 GW scale-up needed to meet 2030 targets. Current capacity at ~6 GW installed globally.

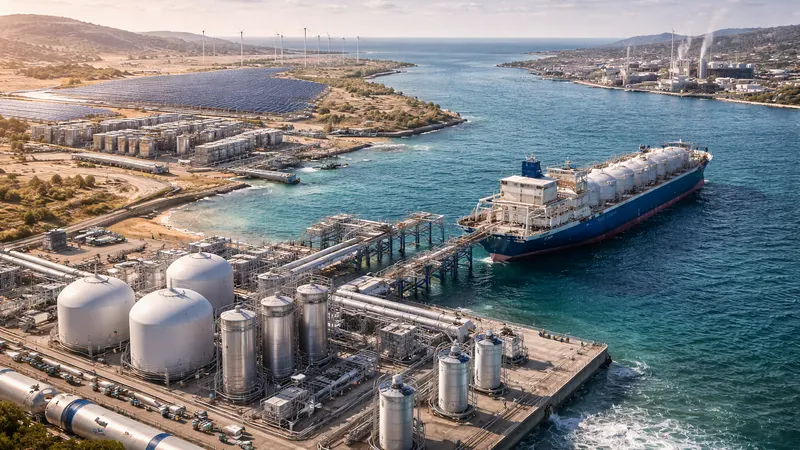
  • Green ammonia synthesis plant with storage tanks

    Green Ammonia Production

    Large-scale green ammonia facilities powered by renewables. Market projected to reach $3.2B+ by 2033 at 25% CAGR — driven by fertilizer decarbonization and maritime fuel demand.

  • Sustainable aviation fuel production facility beside an airfield

    Sustainable Aviation Fuels

    Power-to-liquid pathways leveraging green hydrogen for SAF production — the only viable decarbonization solution for long-haul aviation with mandated blending requirements expanding globally.

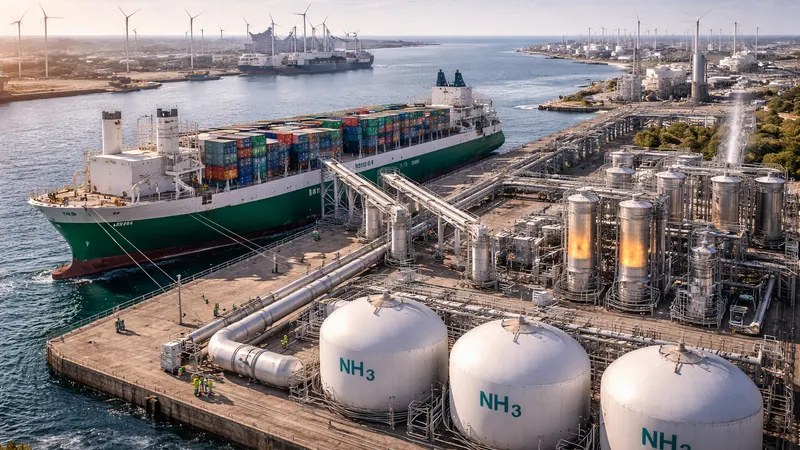
  • Ammonia bunkering infrastructure at a commercial port

    Maritime Fuel Infrastructure

    Ammonia-powered vessel development, port bunkering systems, and cracking technology. IMO 2050 targets drive ammonia to potentially 25% of shipping fuel mix. 50–100 ports need infrastructure by 2030.

  • Solar and wind park co-located with an electrolyzer plant

    Integrated Renewable-to-Molecule

    Co-located renewable generation + electrolyzer parks with hybrid solar-wind improving capacity factors to 55-65%. Hydrogen pipelines 5-7x cheaper than HVDC for energy transport beyond 400 km.

  • Hydrogen pipeline and underground storage facility

    Storage & Pipeline Infrastructure

    Underground salt cavern storage (50-150 GWh per site), hydrogen backbone pipelines (25,000 km needed by 2030 vs. 5,000 km today), and repurposed natural gas infrastructure.

Geographic Focus:

  • United States
  • European Union
  • United Kingdom
  • Japan
  • Australia
  • Middle East
  • India
  • Vietnam

Infrastructure Investment Priorities

Infrastructure Priority Matrix

Investment priorities are sequenced by infrastructure lead times, market certainty, and ROI profiles. Tier 1 represents immediate deployment; Tier 2 targets mid-cycle opportunities; Tier 3 captures long-horizon positioning plays.

TIER 1 — CRITICAL

Highest Conviction, Longest Lead Times

InfrastructureTimelineMarket Impact

Electrolyzer Gigafactories

12-18 mo

Need 15-20 gigafactories (5+ GW each) by 2028. Construction lead time 30+ months demands immediate groundbreaking. Cost curve learning rates drive 20-35% IRR.

30 mo lead time

Industrial Cluster H₂ Pipelines

24-30 mo

Priority corridors connecting industrial hubs to renewable zones. Regulated utility-like returns with multi-offtaker demand. 48-month build cycles require 2026 start.

Industrial Green Hydrogen

18-24 mo

Captive electrolyzers at steel (DRI), refining, and fertilizer plants. Demand exists regardless of grid status. H2 Green Steel, ArcelorMittal, and similar anchor offtakers.

Highest certainty
TIER 2 — HIGH PRIORITY

First-Mover Advantage, Moderate Tech Risk

InfrastructureTimelineMarket Impact

Ammonia Cracking Technology

18-24 mo

First-mover advantage in maritime fueling. Must scale from pilot (100 kg/day) to commercial (10+ tonnes/day). 100-500x scale-up required for shipping demand.

6–8 Year Payback

Co-located Renewable + Electrolyzer Parks

24-36 mo

Hybrid solar-wind plants paired with electrolyzers for 55-65% capacity factors. Economics depend on PPA pricing and hydrogen offtake. 2028-2029 commissioning targets.

3–4 Year Payback

Desalination for Hydrogen

24-36 mo

Co-located seawater desalination for water-scarce hydrogen production zones (Middle East, North Africa, Australia). 9-10 liters per kg H₂ means 225-250M m³/year at scale.

7–10 Year Payback
TIER 3 — STRATEGIC R&D

Long-Horizon Infrastructure Plays

InfrastructureTimelineMarket Impact

Underground H₂ Storage

36-48 mo

Salt caverns providing 50-150 GWh per site for seasonal energy balancing. 2,000 GWh total capacity needed. 60+ month lead times require immediate geological surveys and permitting.

R&D Pilot Lines

Breakthrough Electrolysis R&D

30-36 mo

Low-PGM catalysts (<0.1 mg/cm²), SOEC durability (>40,000 hours), photoelectrochemical water splitting. Remove iridium/platinum bottleneck that caps PEM scale-up.

R&D + Demo

Gas Pipeline Repurposing

36-60 mo

Europe has 200,000+ km gas pipelines. Repurposing at €0.4-0.8M/km vs. €1.5-2.5M/km new build. For seasonal energy transport, hydrogen in existing pipes is cheaper than new HVDC.

  • TIER 1 — CRITICAL

    3 priority targets

  • TIER 2 — HIGH PRIORITY

    3 priority targets

  • TIER 3 — MEDIUM PRIORITY

    3 priority targets

Infrastructure Bottlenecks

Where Capital Meets Constraint — The Investment Thesis

Each bottleneck represents a capital deployment opportunity. The fund's thesis centers on financing the infrastructure that resolves the binding constraints preventing the hydrogen economy from scaling.

  • Fund Gigafactories + Low-PGM Catalyst R&D

    Electrolyzer Manufacturing Capacity

    Roughly 6 GW of electrolyzer capacity is installed globally against a 250-300 GW scale-up needed to meet 2030 targets. 15-20 gigafactories (5+ GW each) are required by 2028, with 30+ month construction lead times — and iridium/platinum catalyst supply caps PEM scale-up.

  • Co-Located Hybrid Parks + Battery Storage

    Grid Integration & Intermittency

    Electrolyzers need 95%+ capacity factors for economics, but renewables deliver 25-40%. Grid-connected projects face curtailment. Co-location and battery pairing are the near-term solution.

  • New Build + Gas Pipeline Repurposing

    Hydrogen Transport & Storage

    Only 5,000 km hydrogen pipelines exist globally vs. 3M+ km natural gas. No large-scale liquid H₂ import facilities. Pipeline embrittlement limits blending beyond 20% H₂.

  • Fund 5-10 Demo Projects + Modular Manufacturing

    Ammonia Cracking at Scale

    Commercial shipping needs 10-50 tonnes H₂/day per refueling station. Current largest facilities: 100-500 kg/day. Catalyst durability limited to 2,000-5,000 hours.

  • Seawater Desalination Co-Location

    Water Availability

    25M tonnes H₂/year = 225-250M m³ water. Many optimal renewable sites (MENA, Australia) are water-scarce. Desalination integration is essential but adds cost.

  • 50+ Regional Training Center Investments

    Skilled Workforce Gap

    Need 300,000+ electrochemical engineers, plant operators, and technicians by 2030. Current training programs produce under 20,000 per year.

What We're Looking For

Investment Criteria for Projects

We actively seek hydrogen and green ammonia projects at FEED or FID stage that address critical infrastructure bottlenecks and demonstrate strong technology readiness.

  • FEED/FID Stage Readiness

    Projects must demonstrate completed FEED studies, validated EPC estimates, secured equipment quotations, and clear pathways to Final Investment Decision.

  • Scalability & Offtake Certainty

    Strong potential for scalable production with contractual offtake agreements from industrial users, utilities, maritime operators, or fertilizer companies.

  • National Hydrogen Strategy Alignment

    Projects aligned with regional hydrogen roadmaps, eligible for CfD mechanisms, production tax credits (IRA Section 45V), or EU Hydrogen Bank instruments.

  • Strategic Partnerships

    Robust partnerships with technology providers (Nel, ITM Power, Siemens Energy), EPC contractors, and government entities securing permits and subsidies.

  • Technology Readiness (TRL 7+)

    Commercially proven or late-demonstration stage technologies. Portfolio approach across Alkaline, PEM, SOEC, and emerging AEM to mitigate technology-specific risk.

  • Financial Projections & Models

    Detailed financial models with validated CapEx/OpEx, sensitivity analyses, IRR/MOIC projections, and bankable engineering reports from recognized consultancies.

Geographic Focus:

  • United States
  • European Union
  • United Kingdom
  • Japan
  • Australia
  • Middle East
  • India
  • Vietnam

Value Creation Strategy

Beyond Capital: Accelerating the Hydrogen Economy

  • Offtake Facilitation

    Connecting projects to industrial offtakers across steel, refining, and fertilizer sectors

  • EPC Partnerships

    Strategic alliances with engineering, procurement, and construction firms

  • Subsidy Capture

    Navigating CfD mechanisms, IRA credits, EU Hydrogen Bank, and national programs

  • Technology Integration

    Connecting electrolyzer manufacturers with renewable developers and grid operators

  • Intelligence Platform

    Setcoin Intelligence research powering deal flow and market positioning

Risk Management

Comprehensive Risk Mitigation

The fund employs rigorous risk management across technology, market, and regulatory dimensions — with FEED/FID stage focus inherently reducing early-stage risk exposure.

  • Technology Execution Risk

    Portfolio diversification across Alkaline, PEM, SOEC, AEM technologies

  • Demand & Offtake Risk

    CfD mechanisms and long-term contracted offtake mitigate volume uncertainty

  • Supply Chain & PGM Constraints

    Catalyst substitution R&D; diversified sourcing; domestic manufacturing

  • Regulatory & Permitting

    Pre-application engagement; fast-track regulatory alignment

  • Geopolitical & Trade Risk

    Multi-geography diversification; sovereign guarantee assessment

  • Water & Environmental

    Integrated desalination; closed-loop water systems; environmental compliance

  • Blue Hydrogen Competition

    Focus on green premium markets, export mandates, and regulatory moats

  • Capital Intensity & Cost Curves

    Staged milestone-based deployment; learning rate assumptions validated

  • Grid vs. Hydrogen Priority

    Sequenced approach: grid-first (2026-28), balanced (2029-32), H₂-scaled (2033+)

Related Intelligence

Frequently Asked Questions

Fund Questions, Answered

What is the DSE Hydrogen & Green Ammonia Fund?

A Luxembourg-domiciled equity fund managed by Setcoin Group that finances hydrogen and green ammonia infrastructure at FEED and FID stage — electrolysis scale-up, green ammonia production, maritime fuel systems, sustainable aviation fuels and integrated renewable-to-molecule projects.

Why FEED and FID stage projects?

At FEED/FID the technical risk has been retired but the capital-intensive build-out still requires institutional deployment. The fund treats 2026–2030 as a build-or-bust window: infrastructure not permitted and started now will not be operational until 2030+.

What are the fund's highest-conviction priorities?

Tier 1 (€80-105B of market need) covers electrolyzer gigafactories (€15-20B, 15-20 factories of 5+ GW by 2028), industrial cluster hydrogen pipelines (€50-60B) and captive industrial green hydrogen at steel, refining and fertilizer plants (€15-25B).

What does a project need to qualify?

Completed FEED studies, validated EPC estimates and equipment quotations, contractual offtake from industrial users, utilities, maritime operators or fertilizer companies, alignment with national hydrogen strategies (CfD, IRA Section 45V, EU Hydrogen Bank), TRL 7+ technology and bankable financial models.

Who can invest?

Qualified institutional investors only.

Where does the fund invest?

United States, European Union, United Kingdom, Japan, Australia, Middle East, India and Vietnam.

How to Start

Ready to Power the Hydrogen Economy?

Whether you're looking to invest in the fund or submit a project for funding consideration at FEED or FID stage, we're ready to start the conversation.

Investor Access Request

Request Access to DSE Hydrogen & Green Ammonia Fund

Request access to participate in the fund targeting critical hydrogen & green ammonia infrastructure bottlenecks

Luxembourg
Domicile
Actively Investing
Status

Contact Information

Organization Details

Investment Interest

Anticipated commitment

Additional Information

Compliance & Consent

Important Disclosure

This form is for informational purposes and does not constitute an offer to sell or solicitation of an offer to buy any securities. Investment in the DSE Hydrogen & Green Ammonia Fund is available only to qualified investors and involves significant risks including potential loss of principal. Past performance is not indicative of future results. All investments are subject to the terms and conditions set forth in the fund's Private Placement Memorandum (PPM).

Venture & Project Submission

Submit Your Hydrogen & Green Ammonia Opportunity

We are actively deploying capital into infrastructure projects across the hydrogen value chain. Submit your project details for evaluation by our investment and technical due diligence teams.

What are you submitting?

Contact Information

Project Overview

Project Stage & Timeline

Current Project Stage

Project Sector

Project Financials

Total Project Cost

Data Room Documentation

Required Documentation for FEED / FID Projects

The following documentation demonstrates project shovel-readiness and enables thorough evaluation with reduced risk and uncertainty. Please confirm availability and provide data room access below.

Documents available in your data room
Risk Assessments: The level of detail and comprehensiveness of your project manual is crucial—it demonstrates shovel-readiness and enables prospective investors and lenders to thoroughly evaluate the opportunity with reduced risk and uncertainty.

Secure link to your existing data room (Intralinks, Datasite, Google Drive, etc.)

PDF or PowerPoint, max 25MB

Submission Consent

Confidentiality Assurance: All submissions are treated as strictly confidential. Your information will only be shared with our investment team for evaluation purposes. We do not share deal flow with portfolio companies or other investors without explicit consent.