Skip to content
Setcoin Group
CLOUD & AI FACTORIES INFRASTRUCTURE

DSE Green Hyperscale Data Centers Fund

Actively deploying capital into next-generation sustainable data infrastructure — from greenfield AI-optimized hyperscale campuses to the €63B liquid cooling retrofit wave transforming operational facilities. The fund targets critical bottlenecks throttling the €622B global datacenter market through 2030: power infrastructure, cooling capacity, and the 40 GW installed base requiring AI-readiness upgrades.

Fund type: DebtStatus: Actively Investing

Setcoin Atlas · live pipeline

The pipeline behind the fund

What the public record shows today in the sectors DSE Green Hyperscale Data Centers Fund invests in. The fund screens from the same Atlas records, and every project is scored on the Bankability Index.

441projects in play: pre-FID with at least one consent gate on the public record10 verified at shovel-ready or later after an in-depth screen
758projects in development (pre-FID)
$1.16tnpre-FID capex (filed or modeled)
203already under construction

By stage (Bankability Index)

  • No gate yet317
  • Award / offtake only15
  • Pre-consent424
  • Shovel-ready2
  • Bankable0

Highlighted rows are in play. Few projects reach shovel-ready or bankable on public evidence alone, because EPC and offtake contracts are rarely published; a Screen on the dataroom moves them. Bars on a square-root scale.

By region

  • Europe & UK529
  • United States170
  • Canada58
  • Middle East & Africa1

Verified shortlist: screened in depth, names withheld

#RegionWorking stageReadinessCapexGates on the record
1United States · TexasFID72$20.0bnlandconsentpermitsgridofftakeepcsponsorcapital
2United States · KentuckyFID66$10.0bnlandconsentpermitsgridofftakeepcsponsorcapital
3United States · VirginiaFID65$3.0bnlandconsentpermitsgridofftakeepcsponsorcapital
4United States · TexasFID59$17.0bnlandconsentpermitsgridofftakeepcsponsorcapital
5United KingdomFID56$3.2bnlandconsentpermitsgridofftakeepcsponsorcapital
6United States · PennsylvaniaFID52$6.0bnlandconsentpermitsgridofftakeepcsponsorcapital
7United States · LouisianaFID52$6.0bnlandconsentpermitsgridofftakeepcsponsorcapital
8United KingdomBankability63$5.2bnlandconsentpermitsgridofftakeepcsponsorcapital
9United KingdomBankability52$13.4bnlandconsentpermitsgridofftakeepcsponsorcapital
10United States · New YorkBankability48$3.6bnlandconsentpermitsgridofftakeepcsponsorcapital

Source: Setcoin Atlas — interconnection queues, permit and state registers, award databases. Figures update with each Atlas build. Named projects, sponsors and evidence are available to registered investors in the LP workspace.

Two Ways to Engage

The Fund is Currently Raising & Actively Investing

Whether you're an institutional investor seeking exposure to sustainable digital infrastructure, or a datacenter developer, portfolio owner seeking growth capital and retrofit financing, we want to hear from you

For Projects & Operators

Submit Your Project

We are actively seeking greenfield datacenter developments, operational facilities requiring AI-readiness retrofits, and cooling infrastructure upgrade projects. If you have a project at Pre-FEED, FEED or FID stage — or an operational facility needing liquid cooling retrofit — we want to hear from you.

  • Debt + Equity financing from €100M to €2B+
  • EaaS retrofit financing (CAPEX → OPEX conversion)
  • Vendor coordination across 15+ equipment categories
  • Fast-track due diligence: 6-9 months vs. 18-24 market standard
  • Access to hyperscaler tenant relationships
  • Strategic vendor partnerships
For Investors

Invest in the Fund

Join leading institutional investors gaining exposure to the green datacenter revolution through a diversified, Pre-Investment Optimized with reduced procurement costs, increased IRR — spanning both new builds and the massive retrofit opportunity.

  • Access to €622B global datacenter market growth
  • Dual strategy: greenfield development + €63B retrofit wave
  • Contracted cash flows with hyperscaler tenants
  • Vendor financing reduces equity base while maintaining cash flows, mechanically improving IRR.
  • CAPEX→OPEX | EaaS converts equipment purchases to operating leases. Improves portfolio company ROIC and reduces leverage ratios.
  • Faster Payback. Lower initial outlay accelerates payback period. Typical infrastructure project payback drops from 4-5 years to 2.5-3 years.

Infrastructure-Constrained Growth

Critical Datacenter Infrastructure Bottlenecks

The datacenter industry's growth is infrastructure-constrained, not demand-constrained. AI workloads require 10x cooling capacity, 3x power density, and specialized workforce skills that don't exist at scale—creating immediate investment opportunities with contracted revenue streams.

15+
Major metro markets with substations at capacity
15-25 GW
Existing capacity needing liquid cooling retrofit
€63B
Base-case retrofit market 2026-2031
18-24
Month transformer lead times choking new builds
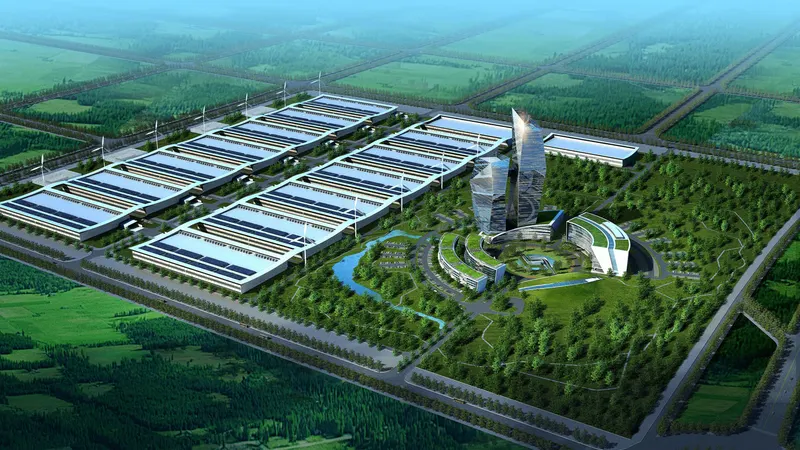
Illustration of a datacenter campus with on-site power generation and nuclear cooling towers

Power Infrastructure Crisis

Critical

AI facilities requiring 50-200 MW face 3-7 year grid queues. Power now 35-40% of project cost (up from 20%). Northern Virginia effectively at capacity.

Investment Opportunity

On-site gas turbine generation (40-60 MW), behind-the-meter renewables+storage, SMR site preparation for 2027-2029 deployment.

Required investment€6-10B
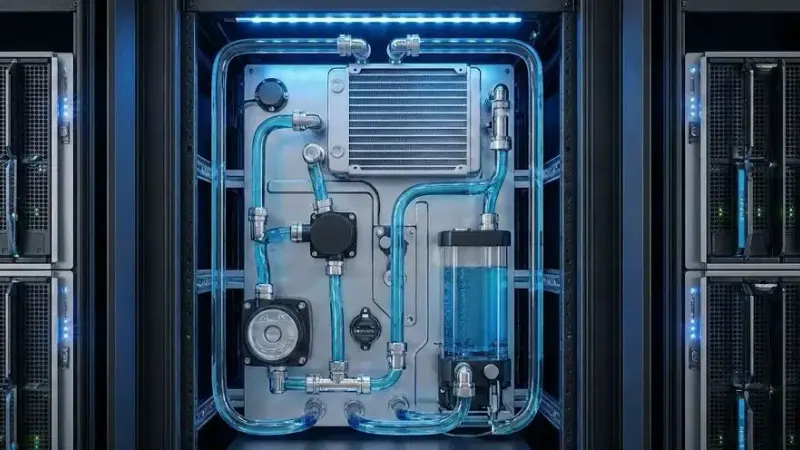
Close-up of liquid cooling manifolds and piping inside a server rack

Cooling Capacity Gap

Critical

GPU racks at 60-120 kW exceed air cooling limits (15 kW). PUE of 1.4-1.6 unacceptable. Fewer than 5,000 certified liquid cooling technicians globally.

Investment Opportunity

Direct-to-chip retrofits ($2-4M/MW), immersion cooling facilities, regional dielectric fluid processing plants (15-20 needed globally).

Required investment€8-12B
Two datacenter engineers in safety vests inspecting a server hall

Physical & Human Constraints

High

Prime connectivity sites 95%+ occupied in top 10 metros. 25,000 operator positions unfilled. Zoning restrictions blocking 20+ major cities.

Investment Opportunity

Prefabricated modular facilities (3-6 mo vs. 18-24 mo build), 75,000 edge micro-sites needed by 2028, workforce training programs.

Required investment€2-3.5B
Server aisle merging into a green vertical farm, symbolising heat reuse

Sustainability Mandates

High

EU mandating PUE <1.3 by 2027. Singapore phasing out water-cooled facilities by 2030. Carbon pricing at €80-100/ton rising.

Investment Opportunity

Heat reuse infrastructure (€20-35/MWh revenue), adiabatic cooling for water-stressed regions, DCIM AI-powered optimization platforms.

Required investment€2-3B
Global logistics network map with shipping, air freight and manufacturing icons

Supply Chain Concentration

Medium

80% of fiber transceivers come from 3 manufacturers. TSMC bottleneck for H100/H200 GPUs. China dependency for rare earth cooling elements.

Investment Opportunity

High-density rack manufacturing expansion, sodium-ion UPS batteries eliminating lithium risk, domestic transceiver production.

Required investment€1.5-3B
Abstract EDGE computing emblem over a dark circuit-board background

Edge Explosion Gap

Medium

50,000-75,000 new 5G edge sites needed by 2028. Autonomous vehicles require <10ms latency. Only mobile-scale infrastructure exists today.

Investment Opportunity

Ruggedized micro datacenter manufacturing (10,000+ units/year), cell tower co-location infrastructure, edge-to-cloud networking.

Required investment€1.5-2.5B

Our Investment Thesis

The datacenter industry's growth is infrastructure-constrained, not demand-constrained. We target both greenfield development in supply-constrained markets and the massive $63B retrofit opportunity — where operational facilities must upgrade from air to liquid cooling to serve AI workloads. Our dual strategy captures value across the entire datacenter lifecycle.

  • Retrofit > Greenfield: $63B retrofit market with 2.8-year payback and 34% IRR. Faster revenue, lower risk, contracted demand.

  • Cooling = New Power: Liquid cooling unlocks 2-3x rack density without new power builds — the fastest path to capacity addition.

  • EaaS Financing: Convert $1-1.5B CAPEX into $150M/year OPEX — making retrofits feasible for operators who can't self-finance.

  • Pre-FEED Advantage: Engage projects at Month 6-12 when specs are flexible — not post-FID when 90% is locked.

  • Strategic Vendor Integration: Package equity + equipment for 5-10% CAPEX savings — developer + vendor + investor triple win.

  • Sustainability Premium: Green-certified assets command 15-20% valuation premium with contracted hyperscaler revenue.

2026-2030 Investment Roadmap

Infrastructure Priority Matrix

Comprehensive analysis of space infrastructure gaps ranked by urgency, investment requirements, and market impact. Lead times of 18-48 months mean decisions made now determine 2030 market leaders.

TIER 1 — CRITICAL

Build Immediately 2026-2030

12-24 month deployment windows

InfrastructureTimelineMarket Impact

Liquid Cooling Retrofits

50,000+ rear door & direct-to-chip systems

6-18 mo

Unlocks 2-3x rack density without new power. Existing hyperscale & colocation facilities. 6-month technician certification programs required. 50,000+ rear door & direct-to-chip systems.

On-Site Power Generation

50-100 gas turbine installations (40-60 MW)

18-24 mo

Grid-constrained: NoVA, Silicon Valley, London, Singapore. 4,000+ MW total capacity. Bypass 3-7 year utility queue with behind-the-meter generation. 50-100 gas turbine installations (40-60 MW).

€2-4B market

Edge Micro DC Manufacturing

Production capacity for 10,000+ units/year

12-18 mo

75,000 sites needed by 2028 for 5G edge. Ruggedized 6-42U self-contained units. Partnerships with tower companies and retail chains. Production capacity for 10,000+ units/year.

€8B market 2026-2028

Workforce Development

15,000 DC technicians & engineers

12-18 mo

30,000 unfilled positions globally. Tier 3/4 technician wages +35% since 2022. Vendor-subsidized certification programs with Vertiv, Schneider. 15,000 DC technicians & engineers.

Critical enabler for all tiers
TIER 2 — HIGH PRIORITY

Critical for 2028-2032

18-36 month deployment windows

InfrastructureTimelineMarket Impact

SMR Site Prep & Deployment

10-15 small modular reactors at DC campuses

24-36 mo

LCOE $60-90/MWh vs. $120-180/MWh grid in constrained markets. First commercial deployments 2027-2029. NuScale licensed, TerraPower, X-energy pipeline. 10-15 small modular reactors at DC campuses.

Grid independence for 200+ MW campuses

Immersion Cooling Fluid Infra

15-20 regional processing & recycling facilities

18-24 mo

PUE approaching 1.05, zero water consumption. 2-phase immersion handling 250+ kW/rack. Closed-loop recycling at 90%+ reuse rate. 15-20 regional processing & recycling facilities.

Zero-water cooling enabler

Submarine Cable + Edge Bundles

Phased array + AI orbit prediction

24-36 mo

Secondary Asian, African coastal, LATAM markets. First-mover advantage in emerging connectivity hubs. Cable + facility integrated offering.

Regional monopoly potential

Heat Reuse Infrastructure

50+ district heating interconnections

18-30 mo

Sell waste heat at $20-35/MWh. Northern Europe, Canada, cold-climate US. 3-5 year payback improving to 2-3 years with carbon credits. 50+ district heating interconnections.

Regulatory mandates in Nordic countries
TIER 3 — MEDIUM PRIORITY

Strategic 2030-2035

24-60 month deployment windows

InfrastructureTimelineMarket Impact

Quantum-Ready Facilities

Ultra-low temp cooling for quantum computing

36-48 mo

5-10 specialized facilities globally. Dilution refrigerators, cryogenic infrastructure. First-mover positions as quantum commercializes 2029-2032. Ultra-low temp cooling for quantum computing.

Next-gen compute ready

Renewable + Storage Microgrids

100+ DC campuses islanded from grid

24-48 mo

US Southwest solar, Nordic wind, Middle East solar. 10 GWh+ storage. Grid services demand response revenue $500K-2M annually per facility. 100+ DC campuses islanded from grid.

Grid independence + revenue stream

Emerging Market DC Networks

India (2,500 MW), SE Asia (1,000 MW), Middle East

24-48 mo

India: Digital India initiative + data localization. Saudi: 500 MW sovereign AI target by 2027. APAC at 18% CAGR — fastest growing region globally. India (2,500 MW), SE Asia (1,000 MW), Middle East.

€28B+ EU modernization by 2028

AI Training Mega-Campuses

100-500 MW single-tenant facilities

30-48 mo

Co-located with renewable power (Texas solar, Iceland geothermal, Nordic hydro). $1.5-3B per 200 MW facility. Hyperscaler anchor tenants. 100-500 MW single-tenant facilities.

€200-350/kW/mo AI premium pricing
  • TIER 1 — CRITICAL 2026

    4 priority targets

    Build immediately, 12-24 months

  • TIER 2 — HIGH PRIORITY 2028-2032

    4 priority targets

    Near-term development

  • TIER 3 — TRANSFORMATIONAL (2030-35)

    4 priority targets

    Strategic positioning

Infrastructure Orchestration

Vendor Financing & EaaS Optimisation

We solve the financing bottleneck that prevents developments & retrofits from happening. By converting €1-1.5B CAPEX into $150M/year OPEX through Equipment-as-a-Service structures, we make billion-dollar upgrades feasible for operators who can't self-finance.

CAPEX → OPEX

Equipment-as-a-Service (EaaS) transforms datacenter economics — making billion-dollar developments & retrofits feasible through structured vendor financing.

Without EaaS (Traditional)

Financing Dead End

Upfront CAPEX
€1.5B
Balance sheet impact
Full capital charge
Decision timeline
18-24 months
Board approval
CEO + Board required
Vendor coordination
Operator manages 15+ vendors
Outcome
60% of retrofits stall
With Setcoin Group EaaS Structure

Orchestrated Solution

Annual OPEX
€150-180M/yr
Balance sheet impact
Operating expense only
Decision timeline
6-9 months
Approval level
VP Operations budget
Vendor coordination
Setcoin Group manages all vendors
Outcome
Revenue in 12-18 months

Optimal Engagement Window

Vendor Engagement Timeline (36-48 Month Development Cycle)

  1. PHASE 1

    Feasibility Study

    Months 0-6

    Too Early. 80% projects die. Site ID & preliminary studies only.

  2. PHASE 2

    Pre-FEED

    Months 6-12

    Strategic. Setcoin Group issues LOI. Equipment specs start. 30-40% win rate.

  3. OPTIMAL WINDOW

    FEED

    Months 12-24

    Best Window. Specs 80-90% locked here. Investor + vendor coordinated. 40-60% win rate.

  4. PHASE 4

    FID

    Months 24-30

    Too Late. 90-95% procurement locked. Only 5-10% win rate for newcomers.

  5. PHASE 5

    Construction

    Months 30-48

    Locked. Retrofit opportunities only if hyperscaler demands liquid cooling.

Triple Win

Value Proposition by Stakeholder

  • For Operators

    Faster, Cheaper Upgrades

    Convert €1.5B CAPEX into €150M/year OPEX. 6-9 month close vs. 18-24 month market standard. Revenue acceleration: AI workload income 2-3 years earlier. 5-10% equipment discount through strategic vendor integration.

  • For Vendors

    Unlocked Deals & Recurring Revenue

    Win €1-2B contracts that would otherwise stall on customer financing. EaaS creates 10-year payment streams vs. one-time sales. 3x faster sales cycles. Early project access at Pre-FEED when specs are still flexible.

  • For Investors

    IRR Improvement +2-6%

    Vendor financing reduces equity base while maintaining cash flows, mechanically improving IRR. Faster payback — typical infrastructure project payback drops from 4-5 years to 2.5-3 years.

THE €63B RETROFIT OPPORTUNITY

Liquid Cooling Retrofit Market

95% of the 40 GW installed datacenter base is air-cooled — yet AI workloads demand liquid cooling. The retrofit opportunity is comparable to greenfield development with better dynamics: 3x faster sales cycles, 1.5-2x higher margins, and less competition.

  • Hyperscalers (AWS, MSFT, Google, Meta)

    4-8 GW

    €8-40B investment. Upgrading for AI training and inference — Microsoft 2-3 GW for Azure AI, Google 1-1.5 GW for TPU v5.

    Timeline: 2026-2028 (aggressive)

  • Colocation (Equinix, Digital Realty, CyrusOne)

    4-7 GW

    €8-35B investment. Attract AI customers (OpenAI, Anthropic, Cohere). Equinix retrofitting 1-2 GW across 240+ datacenters selectively.

    Timeline: 2027-2029 (customer-driven)

  • Enterprise (Banks, Healthcare, Government)

    3-6 GW

    €6-30B investment. AI fraud detection, diagnostics, predictive analytics. Budget-constrained, EaaS financing critical for adoption.

    Timeline: 2028-2032 (slowest cycle)

300 MW Retrofit Economics (Air → Liquid Cooling)

€1.05B
Total retrofit investment
€377M/yr
Annual benefit (OPEX savings + revenue)
2.8 Yrs
Payback period
34%
Internal rate of return

Investment Strategy

Powering the Future of Green Digital Infrastructure

The DSE Green Hyperscale Data Centers Fund deploys a dual-track strategy: greenfield development of AI-optimized, liquid-cooled facilities in supply-constrained markets, and systematic retrofitting of the massive installed base requiring AI-readiness upgrades.

By integrating modular designs, advanced liquid cooling, waste heat recovery, and on-site renewable generation, the fund captures both new-build and retrofit value across the $622B global datacenter market.

Our infrastructure orchestration approach—coordinating investors, vendors, and operators across the 36-48 month development cycle—accelerates deployment timelines by 40-60% while delivering 5-10% CAPEX savings.

  • Liquid Cooling Infrastructure

    Direct-to-chip systems (PUE 1.15-1.25) and 2-phase immersion cooling (PUE 1.05) handling 100-250+ kW/rack. Retrofit kits for existing facilities at $2-4M per MW.

  • On-Site Power Generation

    Natural gas turbines (40-60 MW), SMR preparation for 2027-2029, and behind-the-meter solar+storage systems bypassing 3-7 year grid queues.

  • Waste Heat Recovery

    District heating integration selling waste heat at $20-35/MWh. Greenhouse partnerships in Northern Europe. 3-5 year payback with carbon credit acceleration.

  • Modular & Prefabricated

    Factory-built modules deploying in 3-6 months vs. 18-24 months traditional. 250 kW-2 MW containerized units. 30-40% critical path reduction.

  • AI-Optimized Architecture

    3-phase 480V high-density power distribution. InfiniBand/RoCE GPU cluster fabrics. OCP rack standardization for multi-vendor AI deployments.

  • Strategic Locations

    Solar-rich (US Southwest, Middle East), hydro-powered (Nordic), and geothermal (Iceland) sites with renewable energy access and grid stability.

ESG Commitment

Sustainability at the Core

Article 9 SFDR fund with measurable environmental impact objectives. EU mandates PUE <1.3 by 2027 — our portfolio targets PUE 1.1-1.2 from day one.

  • Environmental

    100% renewable energy targets, net-zero carbon operations, zero-water cooling through immersion technology, heat reuse mandates, and circular economy principles for hardware lifecycle. Target PUE of 1.1-1.2 across portfolio.

  • Social

    15,000+ workforce training positions funded. Local community engagement programs. Digital skills training in emerging markets. Diverse workforce initiatives across 50+ operational facilities.

  • Governance

    Independent board oversight, TCFD-aligned reporting, robust cybersecurity frameworks (ISO 27001, SOC 2, PCI-DSS), and transparent quarterly ESG impact reporting to all stakeholders.

What We're Looking For

Investment Criteria for Projects

We actively seek greenfield datacenter developments, operational facilities requiring retrofit, and infrastructure equipment vendors seeking projects to finance with EaaS

  • Renewable Energy Commitment

    Projects with clear pathways to 100% renewable energy — on-site generation, PPAs, or certified green grid supply. PUE targets of 1.3 or below.

  • Liquid Cooling Technology

    Greenfield facilities designed for liquid cooling from day one, or operational facilities at FEED/FID stage requiring retrofit to direct-to-chip or immersion systems.

  • Scale: 50 MW+ Capacity

    Hyperscale facilities with 50MW+ IT load, or retrofit projects covering 100+ MW installed base. Smaller edge portfolios considered at 10,000+ unit scale.

  • Contracted Revenue or Pre-Lease

    Signed LOIs or pre-lease agreements from creditworthy tenants — hyperscalers, enterprise, or government. Retrofit projects with AI workload demand confirmed.

  • Secured Power & Grid Access

    Confirmed grid connection or on-site generation plans. Priority for projects with behind-the-meter solutions bypassing utility queues.

  • EaaS / Vendor Partnership Ready

    Operators open to EaaS structures for retrofit financing. Strategic vendors seeking integrated equity + equipment packages through Setcoin orchestration.

Geographic Focus:

  • United States
  • European Union
  • United Kingdom
  • Nordics
  • Japan
  • Australia
  • Middle East
  • India

Related Intelligence

Frequently Asked Questions

Fund Questions, Answered

What is the DSE Green Hyperscale Data Centers Fund?

A Luxembourg-domiciled debt fund managed by Setcoin Group that finances greenfield AI-optimized hyperscale datacenters and liquid cooling retrofits of operational facilities.

What types of datacenter projects does the fund finance?

Greenfield datacenter developments at Pre-FEED, FEED or FID stage, operational facilities requiring AI-readiness liquid cooling retrofits, and cooling infrastructure upgrade projects.

What are the minimum criteria for a project submission?

Hyperscale facilities with 50 MW+ IT load (or retrofit projects covering 100+ MW installed base), a clear pathway to 100% renewable energy with PUE of 1.3 or below, liquid cooling design or retrofit plan, contracted revenue or pre-lease from creditworthy tenants, and secured power or on-site generation.

What is the €63B liquid cooling retrofit opportunity?

95% of the 40 GW installed datacenter base is air-cooled, yet AI workloads require liquid cooling. Retrofitting hyperscaler, colocation and enterprise facilities from air to liquid cooling is a €63B base-case market through 2031, with a representative 300 MW retrofit costing €1.05B, returning €377M per year, a 2.8-year payback and 34% IRR.

How does Equipment-as-a-Service (EaaS) financing work?

EaaS converts a €1-1.5B upfront equipment CAPEX into roughly €150-180M per year of operating expense. The operator gets an operating-expense-only balance sheet impact, a 6-9 month decision timeline instead of 18-24 months, and Setcoin Group coordinates all 15+ equipment vendors — so retrofits that would otherwise stall reach revenue in 12-18 months.

Who can invest in the fund?

Qualified institutional investors only — pension funds, sovereign wealth funds, endowments, family offices, insurers, corporates and funds of funds.; terms are set out in the fund's Private Placement Memorandum.

Where does the fund invest geographically?

United States, European Union, United Kingdom, Nordics, Japan, Australia, Middle East and India — prioritising solar-rich, hydro-powered and geothermal sites with renewable energy access and grid stability.

How to Start

Ready to Power the Future of Green Digital Infrastructure?

Whether you're looking to invest in the fund, submit a datacenter project for financing, or explore retrofit partnerships through our EaaS platform, we're ready to start the conversation.

Investor Access Request

DSE Green Hyperscale Data Centers Fund

Request access to participate in the fund targeting sustainable datacenters AI infrastructure with optimised procurements and performances

Luxembourg
Domicile
Actively Investing
Status

Contact Information

Organization Details

Investment Interest

Anticipated commitment

Additional Information

Compliance & Consent

Important Disclosure

This form is for informational purposes and does not constitute an offer to sell or solicitation of an offer to buy any securities. Investment in the DSE Green Hyperscale Data Centers Fund is available only to qualified investors and involves significant risks including potential loss of principal. Past performance is not indicative of future results. All investments are subject to the terms and conditions set forth in the fund's Private Placement Memorandum (PPM).

Venture & Project Submission

Submit Your Green Hyperscale Data Centers Opportunity

We're actively seeking next-generation sustainable data infrastructure—from greenfield AI-optimized hyperscale campuses to liquid cooling retrofit wave transforming operational facilities.

≥10 MW
Min Capacity
PUE ≤1.4
Energy Target
€50M+
Project CAPEX
OECD
Markets

Contact Information

Project Overview

Project Stage & Timeline

Current Project Stage

Project Capacity & Power

Cooling & Efficiency

Technical Details

Project Financials

Total Project Cost | Capital Structure

Financial Projections

Pre-Leasing

Data Room Documentation

Required Documentation for FEED / FID Projects

The following documentation demonstrates project shovel-readiness and enables thorough evaluation with reduced risk and uncertainty. Please confirm availability and provide data room access below.

Documents available in your data room
Risk Assessments: The level of detail and comprehensiveness of your project manual is crucial—it demonstrates shovel-readiness and enables prospective investors and lenders to thoroughly evaluate the opportunity with reduced risk and uncertainty.

Secure link to your existing data room (Intralinks, Datasite, Google Drive, etc.)

PDF or PowerPoint, max 25MB

Submission Consent

Confidentiality Assurance: All submissions are treated as strictly confidential. Your information will only be shared with our investment team for evaluation purposes. We do not share deal flow with portfolio companies or other investors without explicit consent.